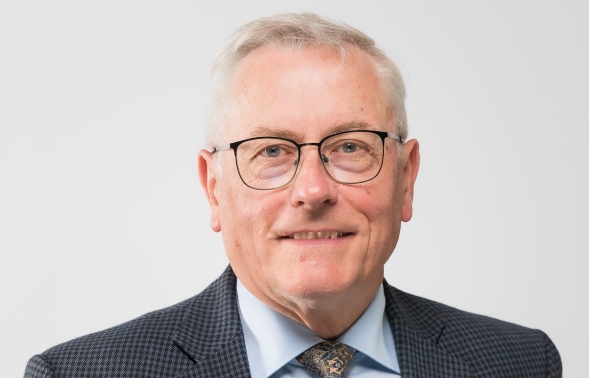
Emeritus Professor Joe Nellis is Head of Economic Research at MHA, the accountancy and advisory firm.
Government borrowing remains historically high with public debt is heading towards £3 trillion, representing around 94% of GDP, and borrowing in September of £24.5 billion reinforces the UK’s fragile fiscal condition ahead of the Autumn Budget.
At the same time, the cost of servicing this debt mountain will be in excess of £110 billion by the end of the financial year as bond yields have climbed to levels not seen since the Global Financial Crisis in 2008. The harsh reality is that debt interest repayments are absorbing scarce resources that could otherwise support public services and much-needed investment.
The government's self-imposed fiscal headroom, introduced by the former Chancellor, Rachel Reeves, has narrowed considerably over the past year, leaving little room for significant tax reductions or additional government spending commitments. Of course, the Chancellor could decide not to restore this headroom, but this would spook the financial markets and send debt-interest rates even higher. This Government is keen to not be ‘in hock’ to the bond markets, but the reality of the situation demands it.
The underlying problem is that the UK economy has struggled in recent years to grow strongly to generate sufficient tax revenues to support the government’s spending commitments. The recent report from the IMF that the UK is likely to grow by 1.3% in 2026 offers a ray of hope but the fact remains that sluggish productivity, disappointing business investment and rising expenditure pressures will continue to place strains on public sector finances in 2027.
It is likely that the Budget will put a lot of attention on the importance of fiscal discipline, tighter spending controls and some further revenue-raising measures – a levy on UK banks is widely expected to restore at least some of the fiscal headroom. However, the Chancellor will also be aware that additional taxation risks weakening business confidence and investment just when the economy needs stronger private-sector growth.