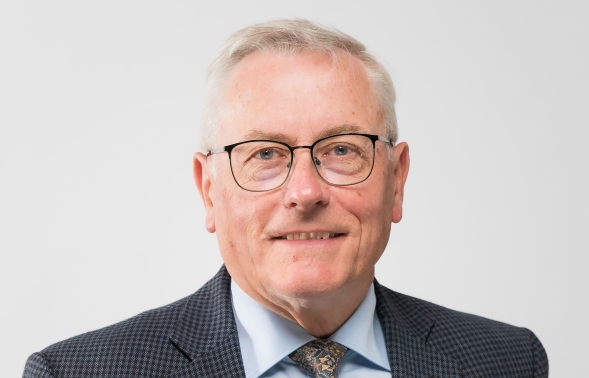
Emeritus Professor Joe Nellis is Head of Economic Research at MHA, the accountancy and advisory firm.
UK unemployment has fallen again to 4.6% in the three months to September, continuing the improvement in August, as strong economic growth across 2027 has increased demand for goods and services and supported job creation in the labour market.
Yet this is unlikely to last. There remain 2.4 unemployed people per vacancy in the UK. Inflation is on the rise and forecast to reach as high as 5% next year, while average wage growth, excluding bonuses, has fallen to 3.5%.
Average wages have been growing at a faster rate than inflation since June 2023, meaning workers have experienced real wage increases and – at least on paper – greater relative household income. But real regular earnings growth has declined to 0.4% and is set to move into negative territory – if not this month, almost certainly in the months ahead. This comes before the anticipated sharp hike in energy bills that will feed through this winter when the energy price cap jumps markedly, with many forecasting it could rise by almost 25%.
This has two key impacts: a decline in households’ spending power will subdue demand in the economy, potentially hitting businesses’ revenue. This could lead to a fall in businesses’ demand for labour, resulting in slowing recruitment and even redundancies, undoing positive shifts in the labour market in recent months.
There is also an inflationary repercussion: a wage-inflation spiral. While workers ask for higher wages to combat rising prices, businesses raise prices to counter their increased employment costs. Both the higher wages and rising prices contribute to inflation in the economy. These are the second-round inflation effects that the Bank of England will aim to control when the MPC next meets on 17 December. With the economy and labour market in a better-than-expected condition, the Bank may feel that the economy can withstand a period of tighter monetary policy, and we can expect another rate hike. While necessary to combat inflation, higher borrowing costs will put an increased strain on business’ finances and the labour market in the months ahead.
Youth unemployment also remains an issue plaguing the labour market, as the full publication of the Milburn report today will outline. Extended periods outside employment or education at a young age can have long-lasting societal and economic effects. The longer you are out of work, the more unemployable you become. The impact extends to the whole economy, leading to wasted talent and a loss of economic potential. As the labour market begins to loosen in the coming months, it is more important than ever that the Government finds a way to provide young people with employment opportunities to avoid losing a generation of workers.