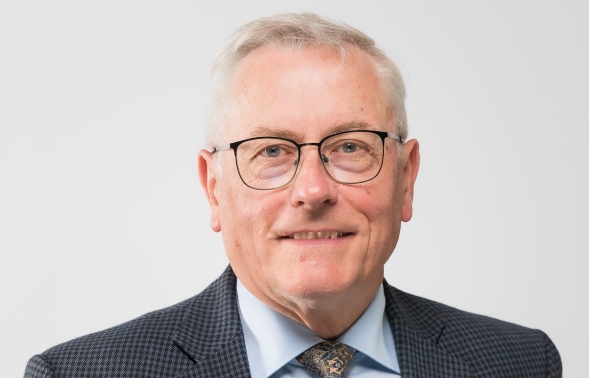
Emeritus Professor Joe Nellis is Head of Economic Research at MHA, the accountancy and advisory firm.
The drop in UK unemployment to 4.7% provides a boost for the economy, reversing a worrying trend marked by falling vacancies and falling confidence.
This follows the upbeat news from the IMF last week that the economy is expected to grow by 1.3% this year, placing the Chancellor in a better-than-expected position as we approach the Autumn Budget.
However, this should not be mistaken for a decisive turning point. The emerging picture for 2027 is one of an economy marked by weak recruitment and cautious business confidence, conditions that are likely to slow down growth in the months ahead.
The labour market continues to face structural issues that are not reflected in the headline data alone.
The number of young people who are not in education, employment or training is a growing concern, with around one million people aged 16-24 now classed as NEETs.
This raises serious questions about the economy's capacity to generate opportunities for new entrants to the workforce, risking creating long-term economic and social costs through lost skills, lower productivity and increased welfare dependency.
Addressing this challenge will require action on three fronts:
- Reduce dependency on the state. Reforming the welfare state must not be viewed simply as a cost-cutting, austerity measure, but as a targeted move that incentivises labour market participation while ensuring people receive the support they need to return to work.
- Equip the next generation with the skills required to keep pace with the changing demands on the modern workforce, but this is a long-term challenge that will not be solved overnight.
- Make it easier for businesses to employ young workers. Measures such as reducing employer NICs for young workers could encourage businesses to recruit and train new entrants to the labour market, but it will cost money that the Treasury may struggle to find.
The Chancellor faces limited fiscal headroom and self-imposed borrowing constraints, while a generally weak – if slightly improved – labour market threatens income tax receipts and increases pressure on welfare expenditure.
The Budget must therefore balance fiscal credibility that satisfies the financial markets while at the same time taking steps to encourage investment, strengthen business confidence and stimulate job creation.